Tax Season on the Reels: What American Players Actually Owe When They Hit It Big
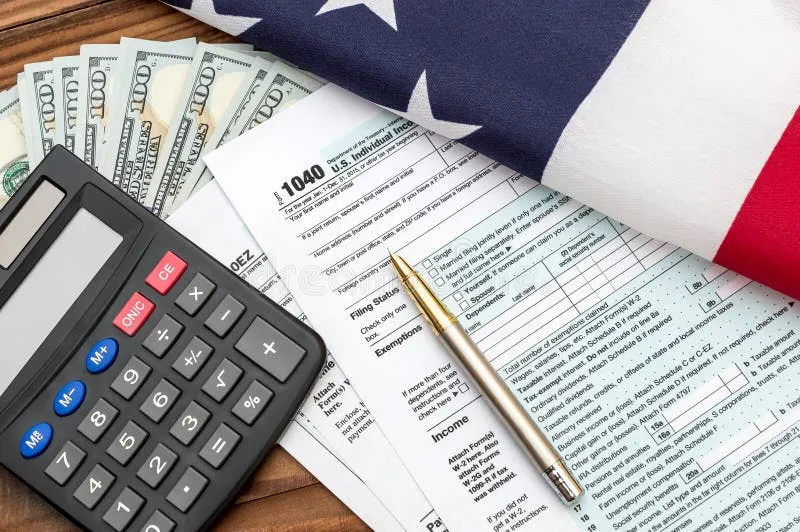
Photo: tax forms calculator casino chips American flag, via thumbs.dreamstime.com
Nobody wants to think about the IRS while the reels are spinning. But if you play slots with any regularity — Fortune Tiger included — tax season is going to find you eventually, and the players who get burned are almost always the ones who assumed the rules worked differently than they actually do.
So let's clear it up, in plain English, before you're staring at a 1040 in February wondering what went wrong.
The Baseline Rule: All Winnings Are Taxable
Start here, because everything else hangs off it: under US federal law, gambling winnings are income. All of them. That $12 hit on a Tuesday night spin counts the same way a $12,000 jackpot counts, at least in principle. The difference is paperwork — the IRS doesn't send anyone a form for twelve dollars, but the legal obligation exists either way.
"A lot of casual players think there's some magic threshold below which winnings don't count," says Denise Hoffman, an enrolled agent who prepares returns for gamblers in Nevada and California. "There isn't. The thresholds only determine who hands you a form at the cage, not whether the income exists."
How W-2G Thresholds Actually Work
The Form W-2G is what a casino or gaming platform issues when a win crosses certain federal reporting limits. For slot play, the trigger is $1,200 or more in a single payout — after the wager is subtracted in most modern implementations.
A few things trip people up:
- It's per payout, not per session. Three $900 wins in an hour generally won't each generate a W-2G on their own; one $1,300 win will.
- Progressive features can aggregate. Some games and platforms combine related payouts, so a single bonus round that pays out in stages can cross the line as one event.
- The form isn't a tax bill. A W-2G just reports the win. What you actually owe depends on your total income, your filing status, and — crucially — your losses.
When a W-2G is issued, 24% federal withholding typically applies to the reported amount, though that's an approximation of your liability, not a final settlement.
The Part Everyone Forgets: Deducting Losses
Here's the rule that changes everything for regular players: you can deduct gambling losses up to the amount of your winnings, provided you itemize deductions on Schedule A.
Say you won $4,000 across the year but lost $3,500 getting there. Without records, you're taxed on the full $4,000. With records — a simple log of dates, amounts, and sessions — you can offset most of it.
"The players who get hurt aren't the ones who won big," Hoffman notes. "They're the ones who won big and can't prove they also lost. The IRS accepts contemporaneous logs. They don't accept 'I remember losing a lot.'"
Your Tracking Checklist
Keep it simple. A note on your phone works:
- Date and platform or casino for each session
- Starting bankroll and ending result
- Any single win over $1,200 (and whether you received a W-2G)
- Screenshots of withdrawal confirmations for online play
If you itemize, hold onto that log all year. If you take the standard deduction, you still report gross winnings as income — the log just helps you know your real number.
What About State Taxes?
Most states tax gambling income too, at rates ranging from zero (states like Texas and Florida) to well over 10% in places like New York and California. A handful — notably Connecticut — have their own W-2G-style thresholds lower than the federal $1,200. If you play regularly, a quick search of your state's rules takes five minutes and can save you a surprise in April.
The Bottom Line
Winning big on Fortune Tiger should feel great. It will feel a lot less great if the first time you think about the tax angle is when your accountant calls. Know the $1,200 single-payout threshold, expect the W-2G when you cross it, keep a loss log from day one, and remember that the deduction side of the ledger is only available to players who bothered to write things down.
The tiger pays in gold. The IRS collects in full. Plan for both.